

The gold price is currently going through a very difficult phase. This has everything to do with tighter financial conditions in the form of a rising US dollar and climbing bond yields. At the time of writing, the dollar index (DXY) is trading at 103.9 points, its highest level in 19 months.
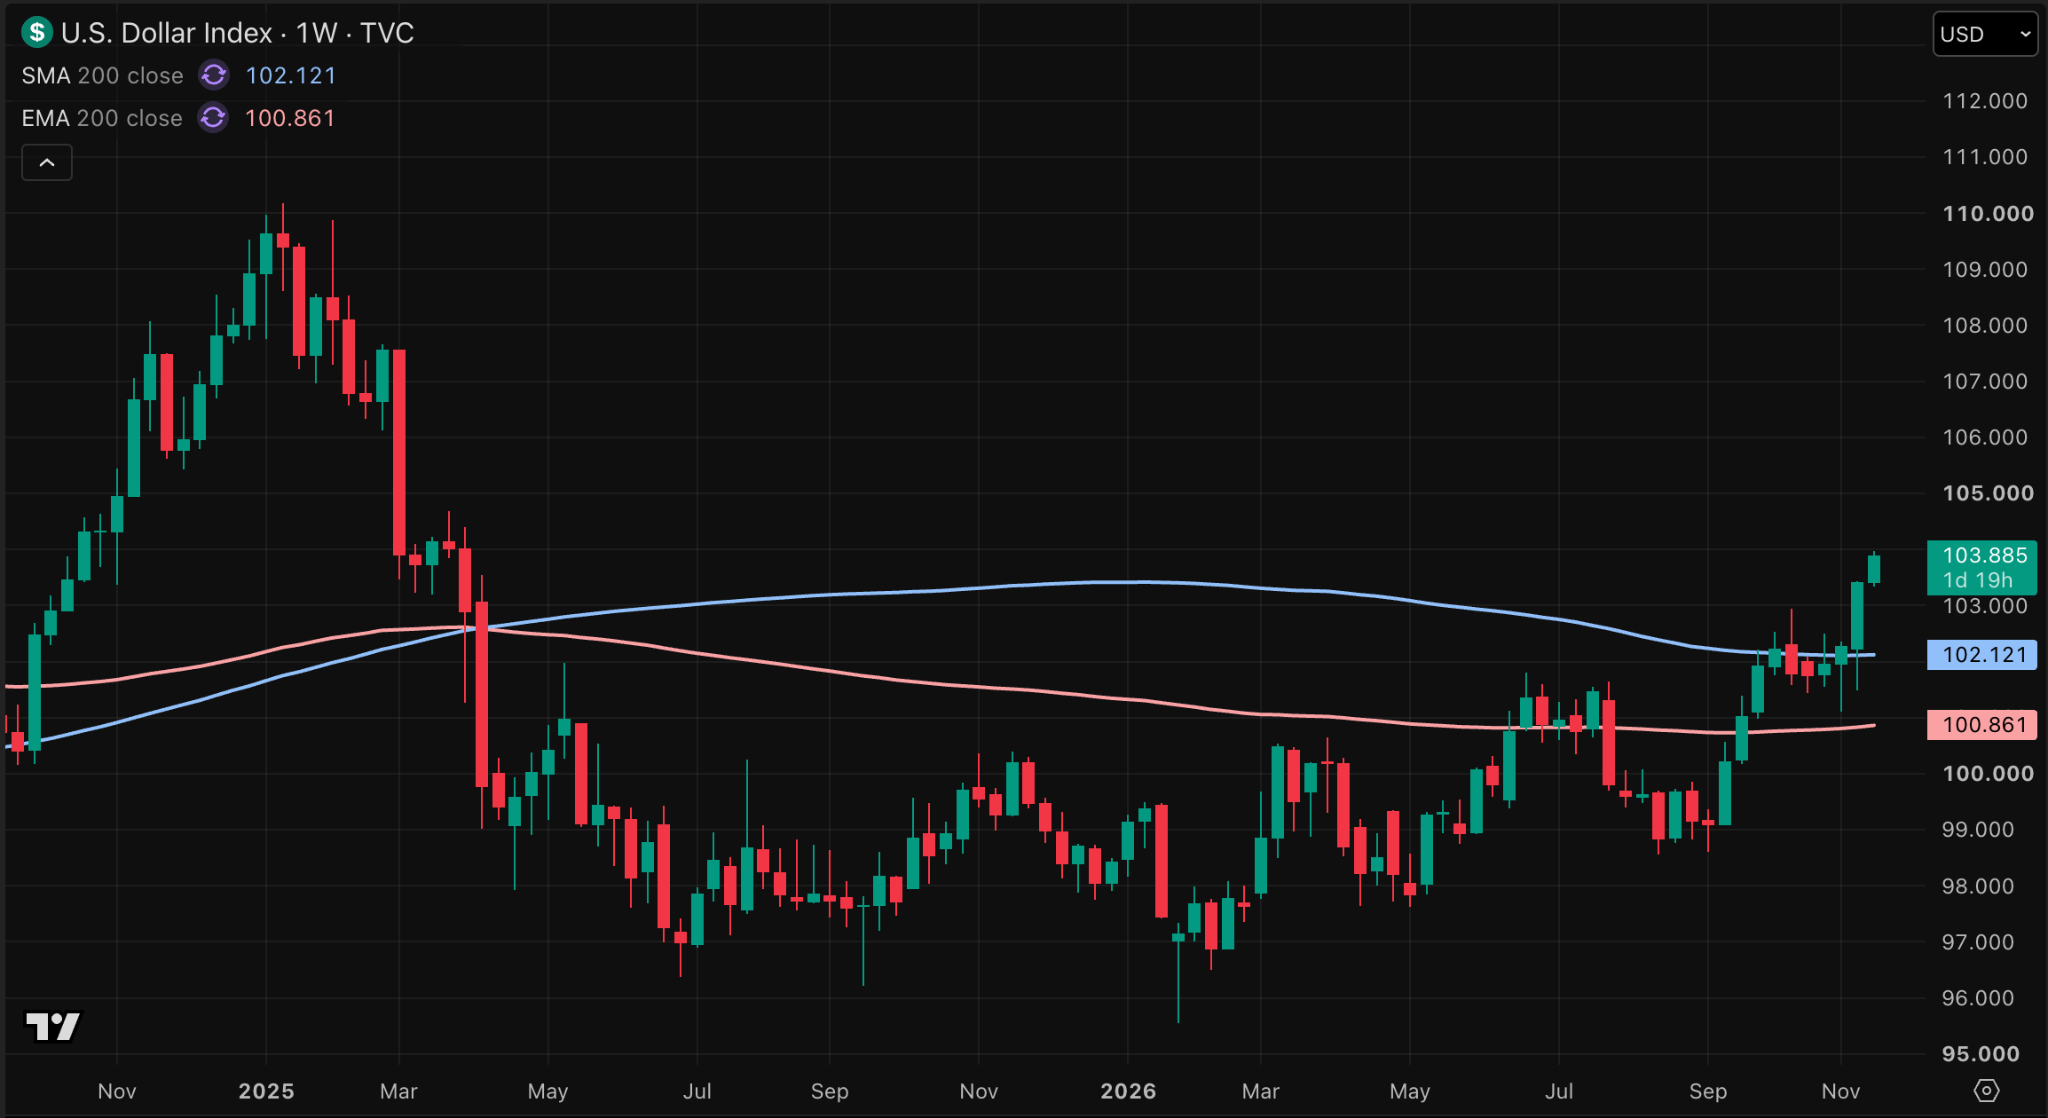
Gold peaked above $5,600 per ounce, while the US dollar hit its lowest level of 2026 at 95.5 points. After that, the dollar began its advance and the gold price came under pressure.
At first, the US dollar recovered after gold pulled back from its peak. The last part of the rally was driven mainly by hype. That air went out of the market. This pushed the gold price down quickly and gave the US dollar its first tailwind.
Then the Iran war began, the oil price climbed at a furious pace, bond yields rose, and the dollar gained even more ground.
After that, the market realized that the AI investment cycle is also a major cause of rising bond yields. The demand for capital is enormous, which allows capital providers to ask for higher interest rates.
Persistent inflation also plays an important role. It depends, among other things, on the sharply higher oil price since February 2026 and on the buildout of AI infrastructure. As a result of persistent inflation, the US central bank has recently become considerably more hawkish.
Until last week, the market was still pricing in roughly two rate hikes through September 2027. Now it is nearly four.
Then Albert Musalem, a member of the US central bank's rate-setting committee, spoke out this week in favor of a scenario with four rate hikes. And this at a time when bond yields had already risen sharply and the US dollar had momentum.
That combination of circumstances dealt the gold price another blow. The important support zone around $4,000 per ounce has now clearly been lost. Gold now appears to be heading toward the 0.50 Fibonacci level of the bull market that began in late 2022 and ended in January 2026.
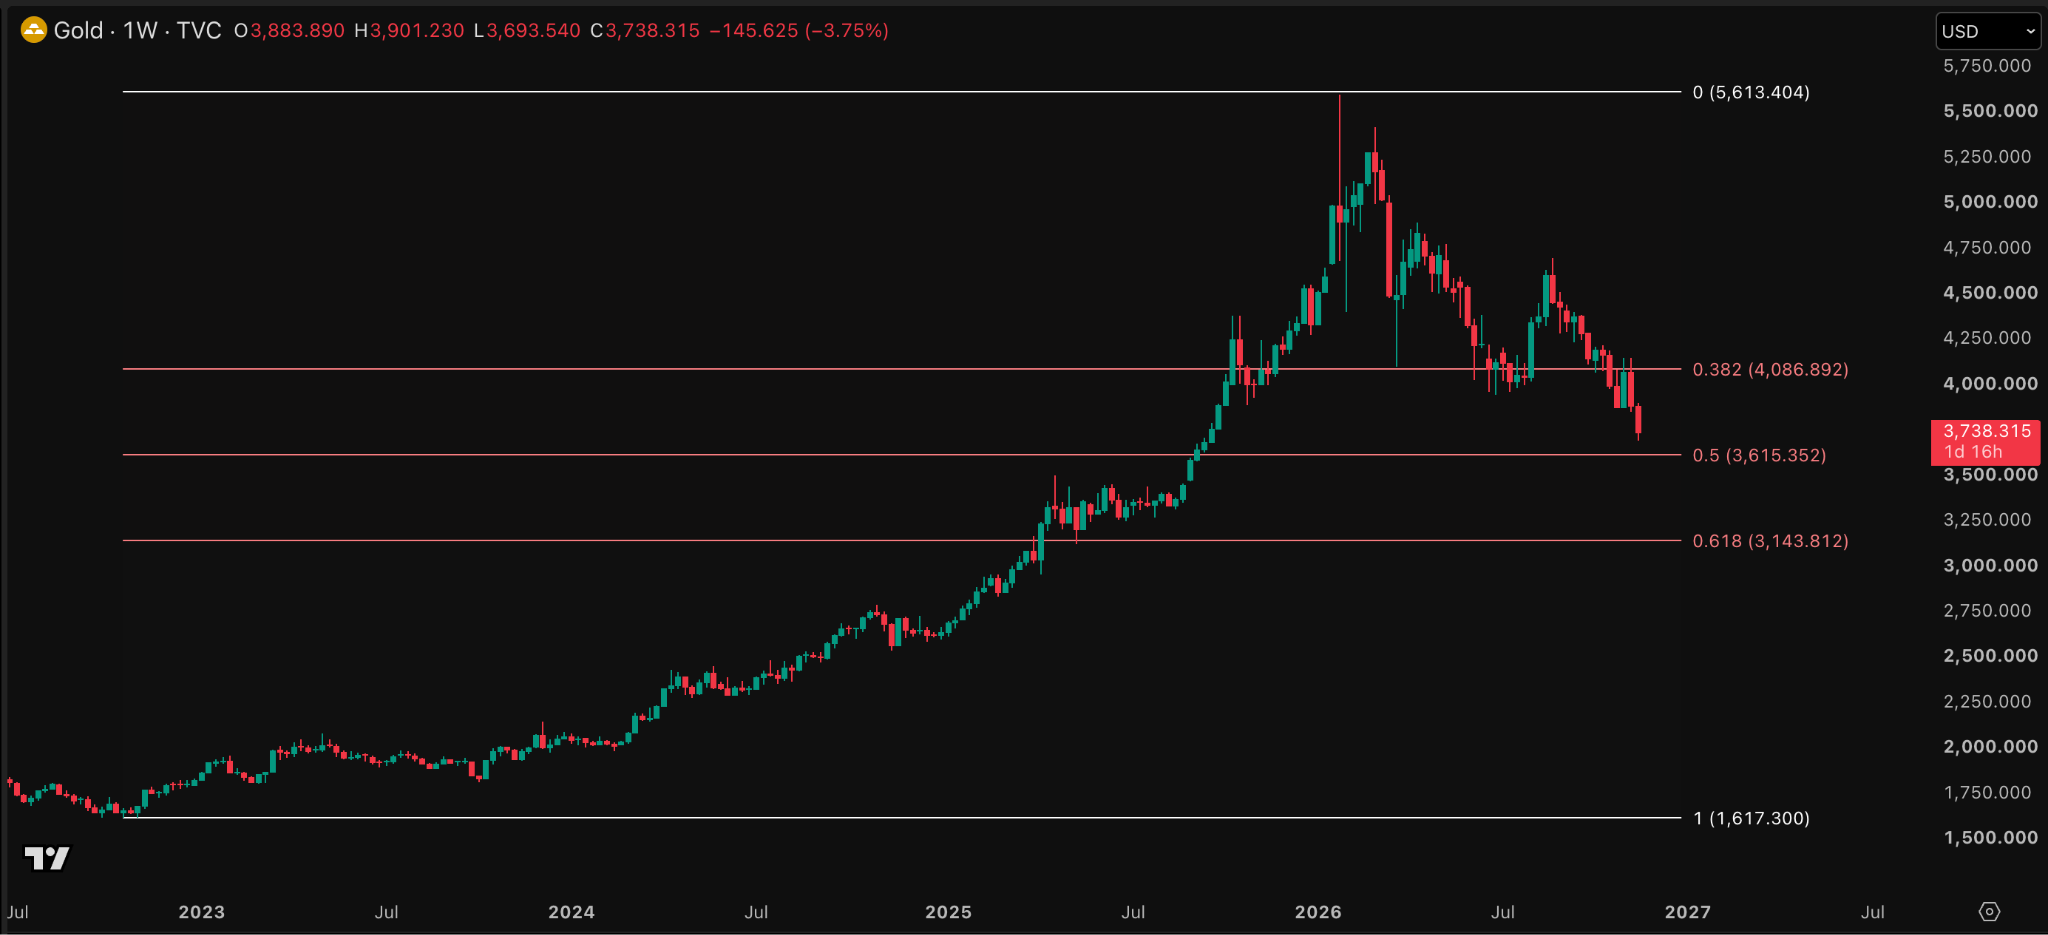
Reaching that level would mean gold has given back 50 percent of the total gain during the bull market. The 0.50 Fibonacci level is typically a point where the market finds renewed support from buyers. For gold, that point is at roughly $3,615 per ounce.
In the shorter term, there is a chance that gold can catch its breath. After the sharp price declines of recent days, the RSI dipped below 30 points yesterday. This means selling pressure is starting to take on fairly extreme proportions.
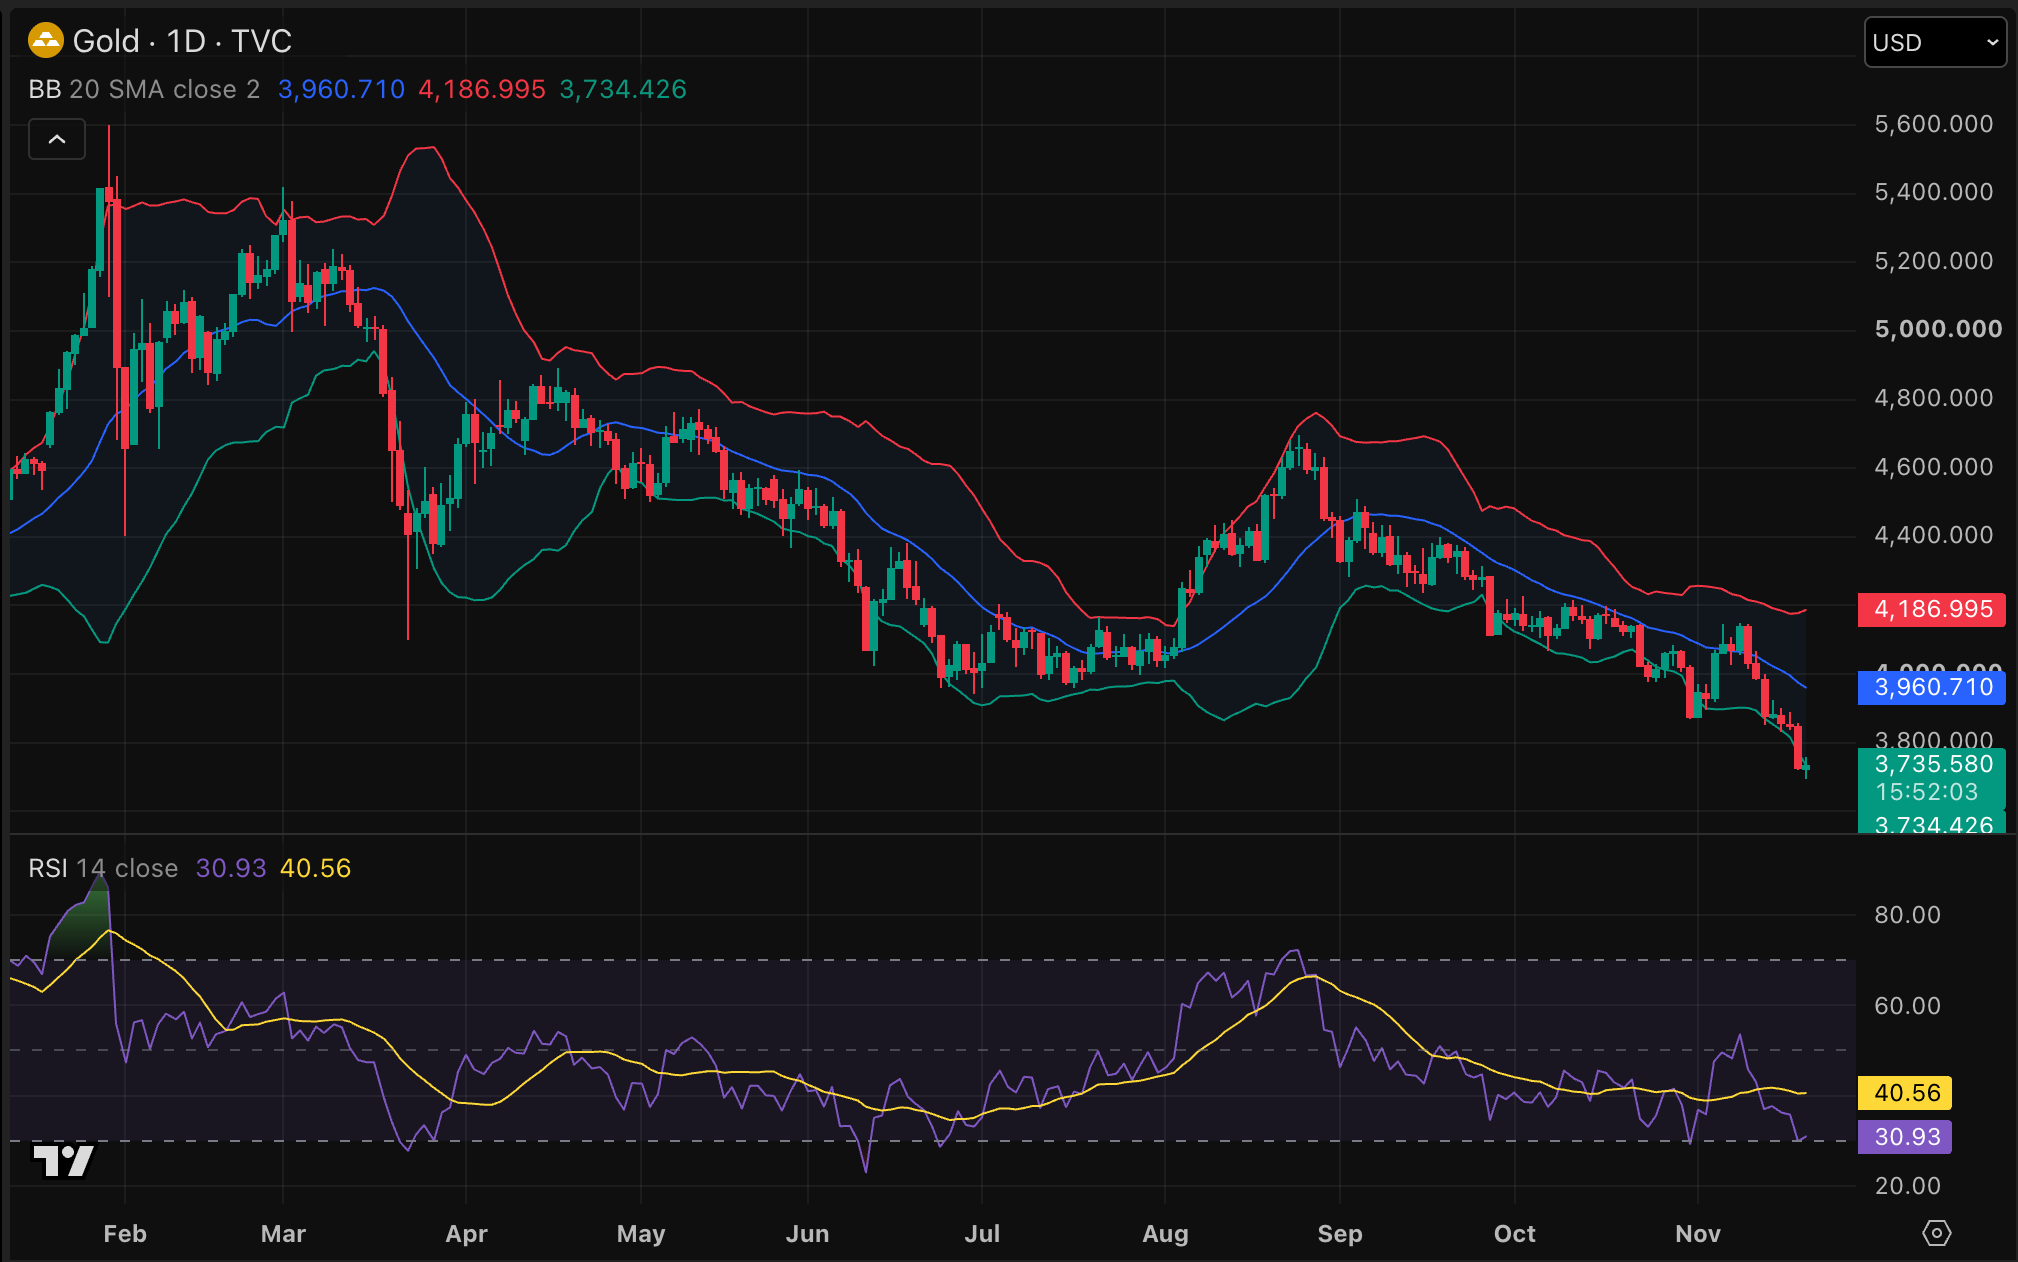
After a series of seven trading days in which the gold price did practically nothing but fall, a recovery could occur in the short term. The RSI, incidentally, is an indicator of the price momentum of a financial asset. For gold, it has become quite oversold.
At the same time, the gold price is trading near the lower edge of its Bollinger Bands, see the chart above. It will be interesting to see whether a support level can be built here for the price. Ultimately, everything depends largely on the US dollar and the extent to which the world's reserve currency can continue its advance.
The strange thing is that, in the long term, these conditions only strengthen the investment case for gold. Rising bond yields mean it becomes even harder for the US government to service its national debt of more than 40 trillion dollars.
Interest costs will rise, which increases the budget deficit, and the US government will probably have to take on even more debt.
In addition, we are currently looking at a more hawkish US central bank, while the market is already doubting the sustainability of the AI investment cycle. If they actually carry out four rate hikes through September 2027, that could endanger the foundation of the US economy.
If the AI cycle comes to a halt, it is probably a matter of time before the US central bank and other major central banks have to step in. So we find ourselves in the strange situation of downward pressure on the gold price in the short term, while the long-term investment story gets stronger.
In the short term, gold is losing ground to the strong U.S. dollar, but oddly enough, that is creating a much more favorable long-term investment outlook for precious metals.
Thom Derks writes for GoldRepublic on gold, macro-economics and geopolitics. He studied Law in Leiden and Economics in Amsterdam. His personal fascination with scarcity and store of value through both bitcoin and gold brought him into the world of financial journalism. Through his own newsletter De Geldpers on Substack, he reaches over 5,800 subscribers with analyses on markets, geopolitics and the monetary system.