

Historically, a well-balanced investment portfolio shows that over the long term it may be possible to achieve a higher return than with saving alone. In this article we look at ways to invest £83,600 wisely, in a way that suits you.
Why diversifying has historically worked better than saving
Investors who diversify their wealth across different financial products are generally more resilient to economic shocks, inflation spikes and financial crises than savers or investors who put all their eggs in one basket.
Saving is safe and gives peace of mind, but in recent years it has returned less than inflation. And in periods of low interest rates (or even negative interest rates, which we experienced in the Netherlands in 2021 and 2022), the purchasing power of savings falls quickly.
Diversification across different asset classes, such as shares, bonds, precious metals and property, means investors are less dependent on the performance of any single product.
Whereas saving is mainly about security and accessibility, diversification is aimed at preserving the purchasing power of your money over the longer term.
Shares & ETFs
For many investors, shares and ETFs are the foundation of a portfolio. That is not without reason, as over the long term shares can generally deliver a higher return.
ETFs make it possible to invest in dozens, hundreds or sometimes even thousands of listed companies at the same time with a single position.
The risk, however, is that shares can be volatile, especially in the short term.
Precious metals: gold, silver and platinum bullion
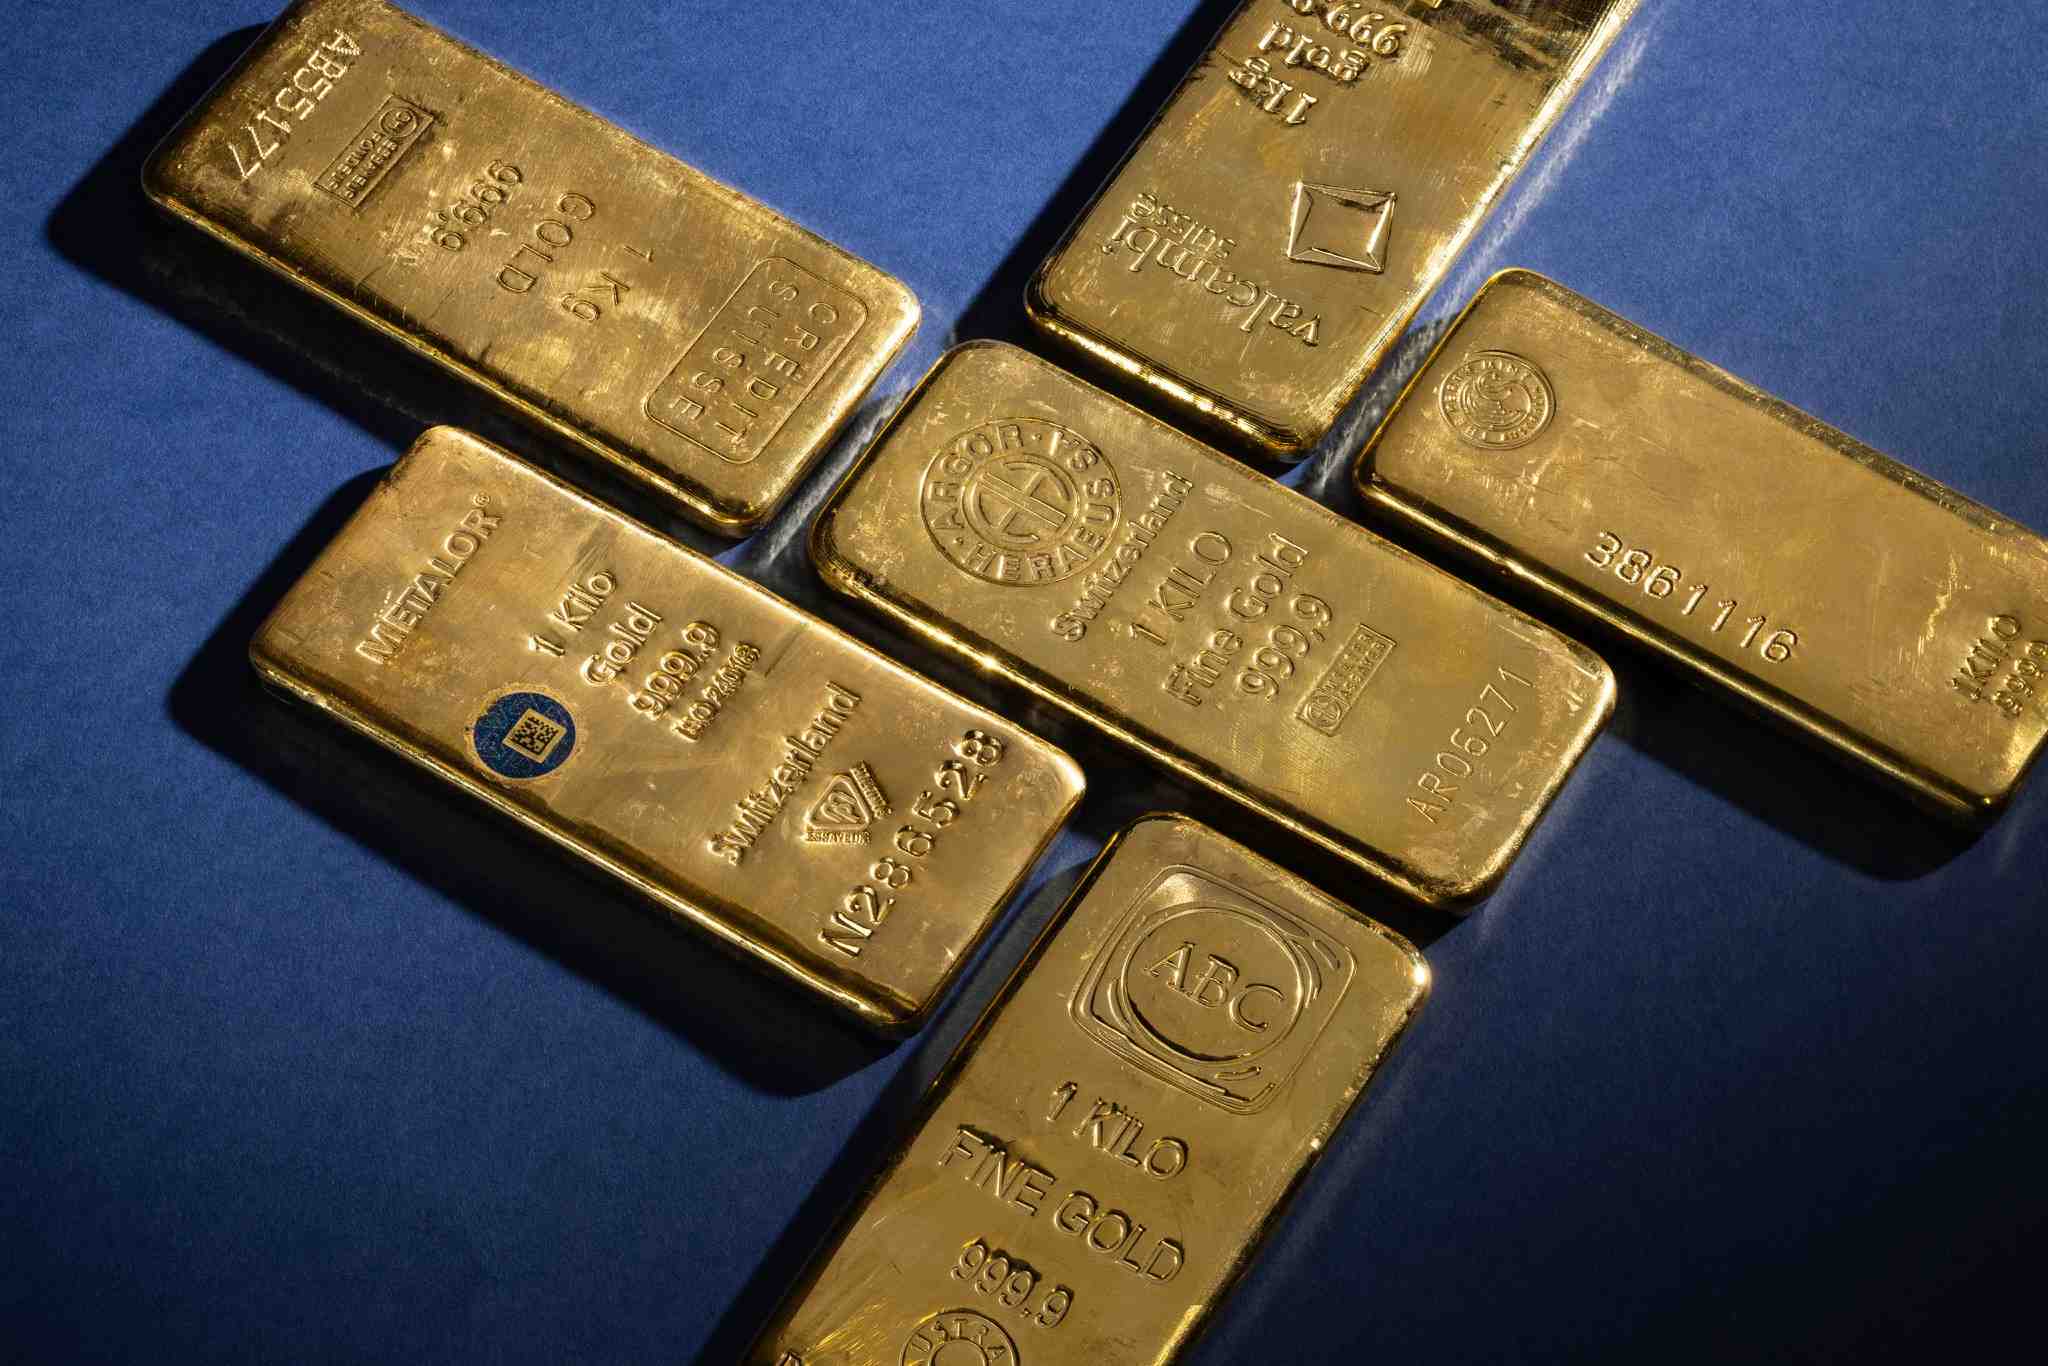
Historically, precious metals have played a protective role within a portfolio. Think of them as an extension of a share portfolio: a stabilising factor in times of inflation, geopolitical unrest and financial crises. While the price of many shares falls in such a period, the price of precious metals tends to rise.
This became clearly visible in 2025, for example, when the prices of gold, silver and platinum went through the roof.
- Gold has served as a monetary anchor for thousands of years. Physical gold bullion is scarce, recognised worldwide and does not depend on a counterparty. In times of inflation, geopolitical unrest or declining trust in banks, gold has proven itself as a store of value, and the gold price has risen.
- Silver combines a monetary function with strong industrial demand. In the coming years, supply of silver is expected to remain structurally too low. The silver price generally moves more erratically than the price of gold, but also offers more opportunity during economic growth and energy transitions.
- Platinum is rarer and more strongly driven by industry. The platinum price is more volatile, but within a portfolio it can be an interesting addition and provide extra diversification.
A portfolio with precious metals: what is a typical allocation?
Although there is no single recommendation, a commonly used allocation in a precious metals portfolio is:
- Gold: +/- 70% (for stability and wealth protection)
- Silver: +/- 20% (more volatile, but interesting because of growing industrial demand)
- Platinum: ±10% (for diversification, and interesting because of growing industrial demand and scarcity)
Investing in precious metals: physical bullion or an ETF?
There are several ways to invest in silver, gold or platinum. For example, through precious metals ETFs or by investing in physical platinum, silver or gold bullion. The crucial difference lies in ownership and counterparty risk.
With physical precious metals, you are the direct owner of a tangible asset. The metal is separate from financial products such as shares or bonds, and therefore carries no financial counterparty risk. The level of risk depends on the chosen form of storage.
At GoldRepublic, bars are stored directly from the refinery in externally managed, independently audited vaults and are fully insured. The quality and presence of the gold are also checked externally.
Are you considering precious metals to complement your portfolio? Book a no-obligation appointment for a personal conversation about allocation, storage and risks.
Savings
Savings are an essential part of every portfolio. It is important to keep a certain portion of your wealth available at all times, without it having lost significant value (as can be the case with investing).
These savings serve as a buffer for unforeseen and planned expenses in the shorter term.
Nibud, the Dutch national budget advice institute, recommends keeping a financial buffer for unforeseen expenses. The exact amount depends on your personal situation, but a common guideline is around six to twelve months of fixed costs. Wealth above this buffer can be used for investing, depending on your risk appetite and financial goals.
Bonds & money market funds
Bonds and money market funds often form the stable part of a portfolio. They are known as a fairly safe investment product and generally offer slightly more return than a savings account.
They are considerably less volatile than most shares, but generally also deliver a lower return.
Moreover, in the Netherlands, bonds and money market funds are taxed as investments, based on a considerably higher notional return than that applied to savings. And because the actual return on bonds and money market funds is often only slightly higher than the savings rate, the tax burden can take a large share of the return.
Pension
A pension is a financial product that is often not seen as a standard part of a portfolio. That is understandable, because money paid into an official pension product is also locked in until you reach the state pension age.
But as your wealth grows, it can be worth setting aside part of it for your retirement.
If you are single in 2026 and your wealth exceeds £48,950, you will start paying box 3 wealth tax on savings and investments. If you have a fiscal partner, this amount is £97,900. At the same time, the annual allowance has been increased significantly in recent years, making additional pension contributions more attractive from a tax perspective. By paying extra into a pension product (such as investing through a pension or an annuity), you move wealth from box 3 to box 1, so that it no longer counts towards wealth tax.
In addition, contributions are often deductible at your marginal income tax rate, while tax is only levied on payout, usually at a lower rate after retirement. Extra pension contributions are therefore of interest to those who want to optimise their tax position, can do without the money for a long time and want to build up wealth for the future in a targeted way.
Alternative investments with higher risks
In addition to the categories above, there are many other ways to diversify your investment portfolio. Examples include investing in property (directly or indirectly, for instance through a property ETF), crowdfunding or private equity.
These categories require more knowledge, longer terms and a higher risk appetite. They are therefore known as products suited mainly to more experienced investors, and as a complement to a portfolio rather than its foundation.
Example portfolios for £83,600
The portfolios below give you an example of how you could spread your £83,600 in a way that suits you: defensive with little risk, neutral, or aggressive with more risk but potentially a chance of a higher return.
They are for illustration only and are not personal investment advice.
Determining your risk profile
A good allocation of your investment portfolio depends on the following three factors, among others:
- Time horizon: the longer you can invest, the more risk you can generally afford to take. Age plays a part here, but it is not the only factor.
- Liquidity: how much money must be available at all times (and should therefore sit in an easy-access savings account)
- Risk tolerance: how do you react to temporary falls in value? Not in theory, but in practice.
Age, income and existing wealth also play a major role.
Growing your wealth beyond £83,600
From this point, the real effect of returns on returns begins. Time in the market matters more than timing. By building positions gradually, for example by buying at regular intervals (also known as dollar-cost averaging), you reduce entry risk and increase the chance of a higher return over the long term.
With GoldRepublic, you can, for example, save in precious metals on a regular basis. Every week, every two weeks or every month, you buy a set amount at the current price. This way you build up a holding of precious metals step by step, expanding your investment portfolio.
In this article, we look at ways to invest a sum of £83,600 wisely, in a way that suits you.
Rika Zaat is host of MacroCheck at GoldRepublic, where she translates macro-economic topics into clear and accessible videos. She is also responsible for marketing, productions and events, including large live evenings with speakers such as Willem Middelkoop and Peter Schiff. Rika graduated cum laude from Nyenrode Business University with an MSc in Financial Management (GPA 8.2).